
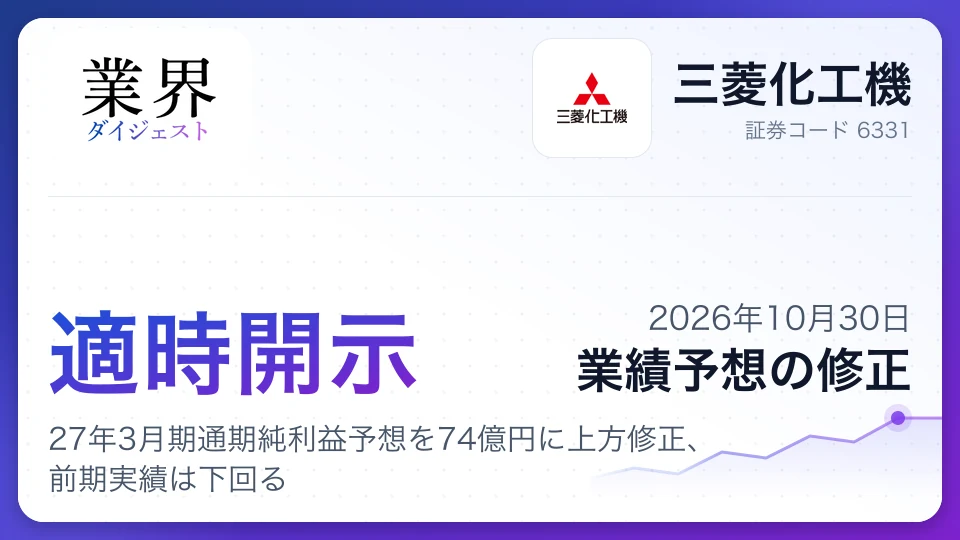
Mitsubishi Kakoki: Lifts FY27 net income forecast to ¥7.45bn
Mitsubishi Kakoki raised its FY ending March 2027 forecasts to ¥83.5 billion in sales, ¥9.5 billion in operating profit and ¥7.45 billion in net income. Sales and net income remain below last year, while operating profit is forecast to rise on a second-half project recovery.
Key facts
- Full-year sales
- ¥83.5bn (previously ¥80bn)
- Operating profit
- ¥9.5bn (previously ¥8.8bn)
- Net income
- ¥7.45bn (previously ¥6.85bn)
- Interim net income
- ¥3.163bn
First-half results miss plan as major projects fall behind
Mitsubishi Kakoki's results for the six months ended September 2026 fell short of the forecasts announced in July for sales, operating profit, ordinary profit and net income. However, each profit measure was higher than in the same period a year earlier.
| Item | Previous forecast | Actual | Year-earlier actual |
|---|---|---|---|
| Sales (¥100 million) | 430 | 380.21 | 361.23 |
| Operating profit (¥100 million) | 42 | 39.17 | 36.81 |
| Ordinary profit (¥100 million) | 43 | 39.10 | 38.64 |
| Interim net income attributable to owners of parent (¥100 million) | 36.9 | 31.63 | 26.79 |
The company said delays in some large-scale projects left sales below forecast. Profit also missed the estimates, although all profit measures topped year-earlier levels. The full-year forecast upgrade assumes the delayed work will catch up in the second half.
Full-year forecast raised, but performance versus last year varies
Mitsubishi Kakoki raised its full-year outlook, but sales, ordinary profit and net income are still expected to fall short of the previous year's actual results. Operating profit is forecast to exceed the prior-year level.
| Item | Previous forecast | Revised forecast | Previous-year actual |
|---|---|---|---|
| Sales (¥100 million) | 800 | 835 | 842.4 |
| Operating profit (¥100 million) | 88 | 95 | 91.81 |
| Ordinary profit (¥100 million) | 89 | 93 | 94.62 |
| Net income attributable to owners of parent (¥100 million) | 68.5 | 74.5 | 75.46 |
| Earnings per share (¥) | 300.69 | 327.03 | 331.34 |
Compared with the previous forecast, the revised estimates are 4.4% higher for sales, 8.0% for operating profit, 4.5% for ordinary profit and 8.8% for net income. Against the previous year's actual results, only operating profit is expected to increase, while sales and net income are set to decline.
Second-half project recovery and cost improvements expected
The company expects to make up for first-half project delays and says previously contracted work and projects won during the current fiscal year, both of which are expected to contribute to second-half sales, are progressing steadily. It has also factored in improvements in construction costs.
- Project recovery: Mitsubishi Kakoki expects to advance projects delayed in the first half and exceed its initial sales forecast.
- Contracted work: Previously contracted projects and work won during the current fiscal year are expected to progress steadily and contribute to second-half sales.
- Cost improvements: The company assumes construction costs will improve, lifting its forecasts for operating profit and other measures.
The revision rests chiefly on recovering project progress in the second half and securing profits through cost improvements. Whether the company can make up for first-half delays is a key factor in meeting its full-year forecast. Mitsubishi Kakoki said its estimates are based on information available at the time of the announcement, and actual results may differ for various reasons.
Share price around the disclosure
Close on disclosure (Oct 30, 2026)
¥2,698
Latest close (Oct 30, 2026)
¥2,698
Reference chart of daily closing prices, not real-time quotes (split-adjusted; weekly closes before the last year). Updated Oct 30, 2026.
Compare Mitsubishi Kakoki with its rivals
Pay, results and share price side by side- vs
 Takuma vs Mitsubishi KakokiTakuma has 2.0x the revenueMitsubishi Kakoki margin 1.6pt higherTakuma pays ¥0.58M moreCompare
- vs
 Mitsui E&S vs Mitsubishi KakokiMitsui E&S has 4.2x the revenueMitsubishi Kakoki pays ¥1.56M moreCompare
- vs
 JGC vs Mitsubishi KakokiJGC has 8.8x the revenueMitsubishi Kakoki margin 6.1pt higherJGC pays ¥0.71M moreCompare
The Plant Engineering industry now
6 companiesMitsubishi Kakoki is one of 6 Plant Engineering companies we cover, #6 by revenue. Here is how the industry’s shares and company plans look:
- Industry shares, 1 year
- +9.8%All industries +14.9%
- Op. profit plan, this FY
- +6.5%All industries +13.0%
- Forecasts raised
- 2cut 0
- Industry op. margin
- 9.0%
- Mitsubishi Kakoki−18.1%
- Plant Engineering (average)+9.8%
- All industries+14.9%
- Latest resultsYear to date through Q1, 4 companies combined: revenue −3.3%, operating profit +85.9% year over year. 1 are ahead of an even pace toward their full-year plan, 4 behind.
- Revisions2 raised and 0 cut this year's forecast. The biggest revision: Mitsubishi Kakoki (operating profit +8.0%).
Tags#Mitsubishi Kakoki#Earnings forecast revision#Fiscal 2027#Full-year results#Interim results#Project progress#Construction costs
Was this article useful?
Anonymous, no sign-up neededComments
The upgrade does not translate into uniform growth from the previous year. Operating profit is forecast to rise, while sales and net income are expected to decline. The outlook depends on making up for first-half project delays in the second half, making progress on contracted work and improving costs. After the interim shortfall, investors will be watching whether work advances as planned.
Cite or share this article
Quoting is free, no permission needed — just credit the source
https://www.gyokaidigest.com/en/disclosures/6331-tdnet-20261030-140120261030561005