Chudenko: To buy back up to 6.93m shares from Chugoku Electric
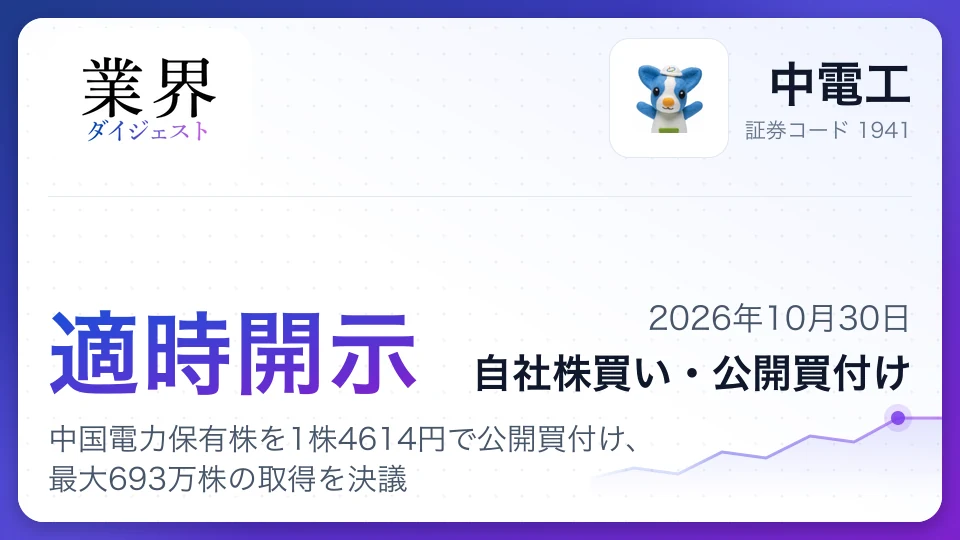
Chudenko will launch a tender offer for shares held by Chugoku Electric at ¥4,614 each, with a cap of 6.93 million shares. Chugoku Electric plans to tender 6.3 million shares, and Chudenko raised its fiscal 2027 dividend forecast to ¥150.
Key facts
- Total value
- Up to about ¥31.975bn
- Offer price
- ¥4,614 per share
- Discount
- 10% to the three-month average
- Planned tender
- Chugoku Electric: 6.3 million shares
- Offer period
- Nov. 2 to Dec. 1, 2026
- Annual dividend
- ¥150, up ¥10 from the previous forecast
Offer price set at 10% discount to market
Chudenko plans to conduct a tender offer for some of the shares held by Chugoku Electric, pricing them at a discount of about 10% to market.
The offer price compares with the closing price before the board decision and average share prices over several periods as follows:
| Share price benchmark | Benchmark price (yen) | Offer-price discount |
|---|---|---|
| Oct. 29 close | 5,230 | 11.78% |
| One-month average | 5,152 | 10.44% |
| Three-month average | 5,127 | 10.01% |
| Six-month average | 5,096 | 9.46% |
Chudenko set the price based on the three-month average. If tenders exceed the maximum number of shares sought, the company will accept shares on a pro rata basis, so it may not acquire all of Chugoku Electric’s tendered shares. The offer will run for 20 business days, with settlement scheduled to begin on Dec. 23.
Chudenko to reshape capital ties with top shareholder
The tender offer is intended to optimize Chudenko’s capital relationship with its top shareholder, Chugoku Electric, and help increase the value of both companies. Chugoku Electric has indicated that it plans to tender some of its shares. If all of its tendered shares are acquired, Chugoku Electric’s stake is expected to fall from 41.34% to 33.40% or more. The utility will remain a major shareholder, although its stake will be reduced.
- Rationale for talks: The companies agreed to strengthen cooperation in grid-scale battery storage and data center businesses, alongside ensuring a stable power supply, while maintaining management independence and autonomy.
- Offer size: The cap is about 10% above the number of shares Chugoku Electric plans to tender. Chudenko said the additional capacity gives other shareholders an opportunity to participate and allows for pro rata allocation if tenders exceed the cap.
- Board process: One of the 11 directors, who also serves as an officer of Chugoku Electric, did not take part in deliberations or the vote to avoid a conflict of interest. The other 10 directors approved the decision unanimously.
Chudenko calculated the offer price based on the market share price and did not obtain a share valuation report from an independent third-party valuation firm. Investors will also want to assess the objectivity of the pricing and its impact on shareholders who do not tender.
Higher shareholder returns, with shares slated for cancellation
Chudenko will fund the purchase entirely with its own cash and plans to cancel all or some of the shares acquired after the offer is completed. It also raised its annual dividend forecast, expanding shareholder returns. The annual dividend will rise by ¥10.
- Purchase funding: The maximum purchase consideration is about ¥31.975 billion. Chudenko estimates that total funding, including fees and other expenses, will be about ¥32.028 billion.
- Financial capacity: Consolidated cash and cash equivalents stood at ¥43.605 billion as of the end of March 2026. Chudenko said it can carry out the offer without adversely affecting its business operations or financial soundness.
- Cancellation plan: Chudenko plans to cancel all or some of the acquired shares following a board resolution. It will disclose the number of shares and timing once decided.
- Dividend forecast: Chudenko raised its annual dividend forecast for the fiscal year ending March 2027 to ¥150 from ¥140. It expects an interim dividend of ¥70 and a year-end dividend of ¥80.
In April 2026, Chudenko set a shareholder-return benchmark of about ¥40 billion over the period of its current medium-term management plan, including ¥22 billion in dividends and an ¥18 billion share buyback framework. The maximum value of this offer exceeds the buyback framework on a simple amount comparison. How Chudenko balances capital allocation with growth investment will remain in focus.
Share price around the disclosure
Close on disclosure (Oct 30, 2026)
¥5,060
Latest close (Oct 30, 2026)
¥5,060
Reference chart of daily closing prices, not real-time quotes (split-adjusted; weekly closes before the last year). Updated Oct 30, 2026.
Compare Chudenko with its rivals
Pay, results and share price side by side
The Construction & Real Estate industry now
61 companiesChudenko is one of 61 Construction & Real Estate companies we cover, #42 by revenue. Here is how the industry’s shares and company plans look:
- Industry shares, 1 year
- +3.4%All industries +14.9%
- Op. profit plan, this FY
- +1.5%All industries +13.0%
- Forecasts raised
- 11cut 0
- Industry op. margin
- 10.1%
- Chudenko+20.2%
- Construction & Real Estate (average)+3.4%
- All industries+14.9%
- Latest resultsYear to date through Q1, 33 companies combined: revenue +7.2%, operating profit +17.1% year over year. 5 are ahead of an even pace toward their full-year plan, 28 behind.
- Revisions11 raised and 0 cut this year's forecast. The biggest revision: YURTEC (operating profit +16.9%).

Tags#Chudenko#Japan equities#Share buyback#Tender offer#Chugoku Electric#Shareholder returns#Dividend#Capital allocation
Was this article useful?
Anonymous, no sign-up neededComments
The tender offer uses a discounted market-based price to acquire shares from a major shareholder, combining a review of capital ties with a reduction in shares outstanding. If Chudenko cancels the shares it acquires, per-share metrics could improve. However, the offer cap of about ¥31.975 billion exceeds the ¥18 billion buyback framework set out in April 2026 on a simple comparison. Investors will look for further explanation of how the offer fits with the existing shareholder-return policy and how Chudenko will allocate capital between returns and growth investment.
Cite or share this article
Quoting is free, no permission needed — just credit the source
https://www.gyokaidigest.com/en/disclosures/1941-tdnet-20261030-140120261029559577