
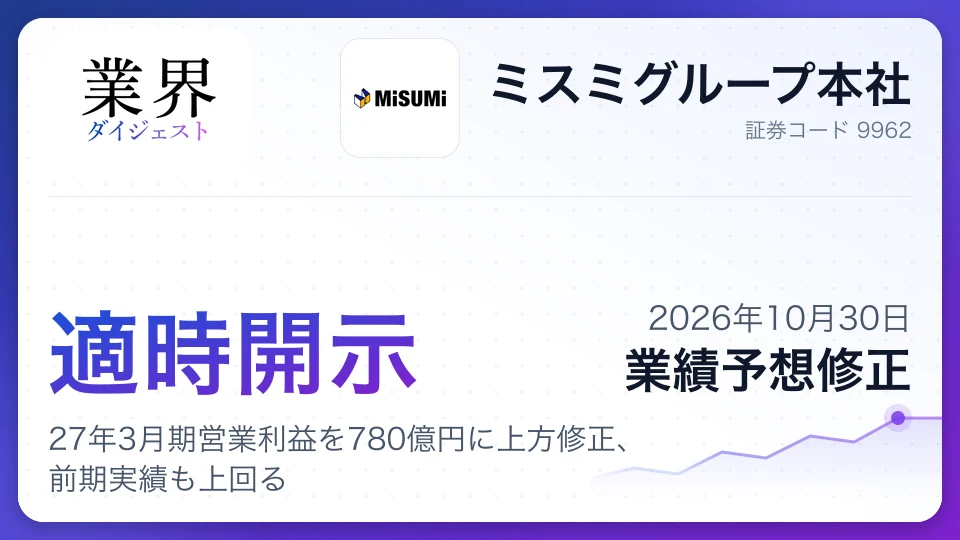
Misumi: Lifts FY2027 operating profit forecast to ¥78bn
Misumi raised its FY2027 sales forecast to ¥565bn, operating profit to ¥78bn and net profit to ¥52.4bn. The increases of 6.2%, 16.4% and 17.0% from July's estimates reflect digital initiatives and strong data center and semiconductor demand.
Key facts
- Sales forecast
- ¥565bn
- Operating profit
- ¥78bn
- Ordinary profit
- ¥77.8bn
- Net profit
- ¥52.4bn
- EPS
- ¥199.98
Profit forecasts lifted more sharply than sales
Misumi raised its consolidated full-year forecasts for the fiscal year ending March 2027. The previous estimates, revised forecasts and prior-year results are as follows.
| Metric | Previous forecast | Revised forecast | Prior-year actual |
|---|---|---|---|
| Sales (¥100m) | 5,320 | 5,650 | 4,413.83 |
| Operating profit (¥100m) | 670 | 780 | 476.13 |
| Ordinary profit (¥100m) | 673 | 778 | 490.95 |
| Net profit (¥100m) | 448 | 524 | 404.57 |
| Earnings per share (¥) | 169.67 | 199.98 | 149.30 |
Compared with the previous forecasts, sales are up 6.2%, operating profit 16.4%, ordinary profit 15.6% and net profit 17.0%. The revised forecasts for sales through net profit all exceed the prior-year results. Profit forecasts have been raised by more than the sales forecast, reflecting expected gains beyond sales growth.
Digital initiatives and related investment demand provide a tailwind
Misumi cited the stronger-than-expected pace and continued impact of its digital model initiatives. The company incorporated the following factors into its forecasts.
- Digital model initiatives: Fictiv, Economy Series, D-JIT and meviy are delivering benefits faster than expected, and those effects are continuing.
- Demand trends: Demand is strong, supported by investment in data centers and semiconductor-related areas.
- Business environment: Uncertainty persists, including geopolitical risks.
Favorable demand and the impact of several digital initiatives were the main reasons for the upward revision. Misumi also noted the uncertain business environment, saying its forecasts reflect information available at the time of the announcement.
Second-half foreign exchange assumptions and forecast caveats
For the average exchange rates from Oct. 1, 2026, to March 31, 2027, Misumi used the following assumptions.
- U.S. dollar: ¥155.0 per dollar.
- Euro: ¥175.0 per euro.
- Chinese yuan: ¥22.5 per yuan.
These are the foreign exchange assumptions for the second half included in the full-year forecast. Actual results may differ from the forecast due to various factors. Misumi said it will promptly disclose any event requiring a forecast revision, including changes in the business environment.
Share price around the disclosure
Close on disclosure (Oct 30, 2026)
¥3,925
Latest close (Oct 30, 2026)
¥3,925
Reference chart of daily closing prices, not real-time quotes (split-adjusted; weekly closes before the last year). Updated Oct 30, 2026.
Compare Misumi with its rivals
Pay, results and share price side by side- vs
 Misumi vs ASKULMisumi has 1.1x the revenueMisumi margin 15.1pt higherMisumi pays ¥1.98M moreCompare
- vsMisumi vs MonotaROMisumi has 1.3x the revenueMonotaRO margin 3.0pt higherMisumi pays ¥2.07M moreCompare
- vsMisumi vs TRUSCOMisumi has 1.4x the revenueMisumi margin 3.7pt higherMisumi pays ¥1.61M moreCompare

The Specialized Trading Company industry now
35 companiesMisumi is one of 35 Specialized Trading Company companies we cover, #20 by revenue. Here is how the industry’s shares and company plans look:
- Industry shares, 1 year
- +24.7%All industries +14.9%
- Op. profit plan, this FY
- +11.0%All industries +13.0%
- Forecasts raised
- 14cut 2
- Industry op. margin
- 3.0%
- Misumi+62.7%
- Specialized Trading Company (average)+24.7%
- All industries+14.9%
- Latest resultsYear to date through Q1, 18 companies combined: revenue +12.3%, operating profit +35.3% year over year. 7 are ahead of an even pace toward their full-year plan, 7 behind.
- Revisions14 raised and 2 cut this year's forecast. The biggest revision: Misumi (operating profit +41.8%).
Tags#Misumi#Earnings forecast revision#FY2027#Machine parts#Digital initiatives#Data centers#Semiconductors
Was this article useful?
Anonymous, no sign-up neededComments
The upward revision is larger for operating and net profit than for sales, indicating that Misumi has factored the growing impact of its digital initiatives and strong related demand into its profit outlook. The company cautioned that uncertainty, including geopolitical risks, remains. Investors will be watching whether the initiatives and demand can sustain their momentum, as well as how exchange rates compare with the stated second-half assumptions.
Cite or share this article
Quoting is free, no permission needed — just credit the source
https://www.gyokaidigest.com/en/disclosures/9962-tdnet-20261030-140120261029560018
Related articles
More on Misumi
- Corporate Restructuring and Subsidiary EstablishmentSep 17, 2026Misumi: Invests $40M in North American AI Supply Chain Hub
- Strategic InvestmentSep 17, 2026Misumi: Launches $50 Million US CVC Fund to Back Robotics Startups
- IndustryFY2026B2B E-Commerce and MRO FY2026 Full Year: MonotaRO leads, ASKUL falters
Latest from B2B E-Commerce & MRO
- EarningsASKULQ1 FY2027ASKUL Q1 FY2027: Revenue drops, yet full-year guidance held as recovery continues
- EarningsMonotaROQ2 FY2026MonotaRO Q2 FY2026: Revenue climbs 20.6% on customer gains, outlook unchanged
- EarningsOtsukaQ3 FY2026Otsuka Q3 FY2026: Sales and profits hit four-year highs
- EarningsTRUSCOQ3 FY2026TRUSCO Q3 FY2026: Sales jump 12%, but profit growth trails
- Monthly Sales ReportMonotaROSep 10, 2026MonotaRO: August sales surge 19.3% as B2B EC growth accelerates amid fierce competition.